In Bezug auf die Markt für containerisierte Umspannwerke, hat dieser in den letzten sechs Jahren ein erhebliches Wachstum verzeichnet (d. h. von einem Nischenprodukt zu einer typischen Lösung), jedoch gab es eine deutliche Verzögerung in Bezug auf tatsächliche Marktforschung zu dieser Produktkategorie. Drei im Jahr 2026 veröffentlichte Berichte, jeweils von drei großen Beratungsunternehmen, haben den Markt für containerisierte Umspannwerke auf drei unterschiedliche Größen geschätzt: 1,3 Milliarden USD, 3,3 Milliarden USD und 3,5 Milliarden USD. Der Unterschied zwischen diesen drei Schätzungen ist nicht nur eine geringe Rundung. Daher ist die bessere Information für einen Käufer das Verständnis der Unterschiede in den Bereichen Umfang und Gesamtschätzung.
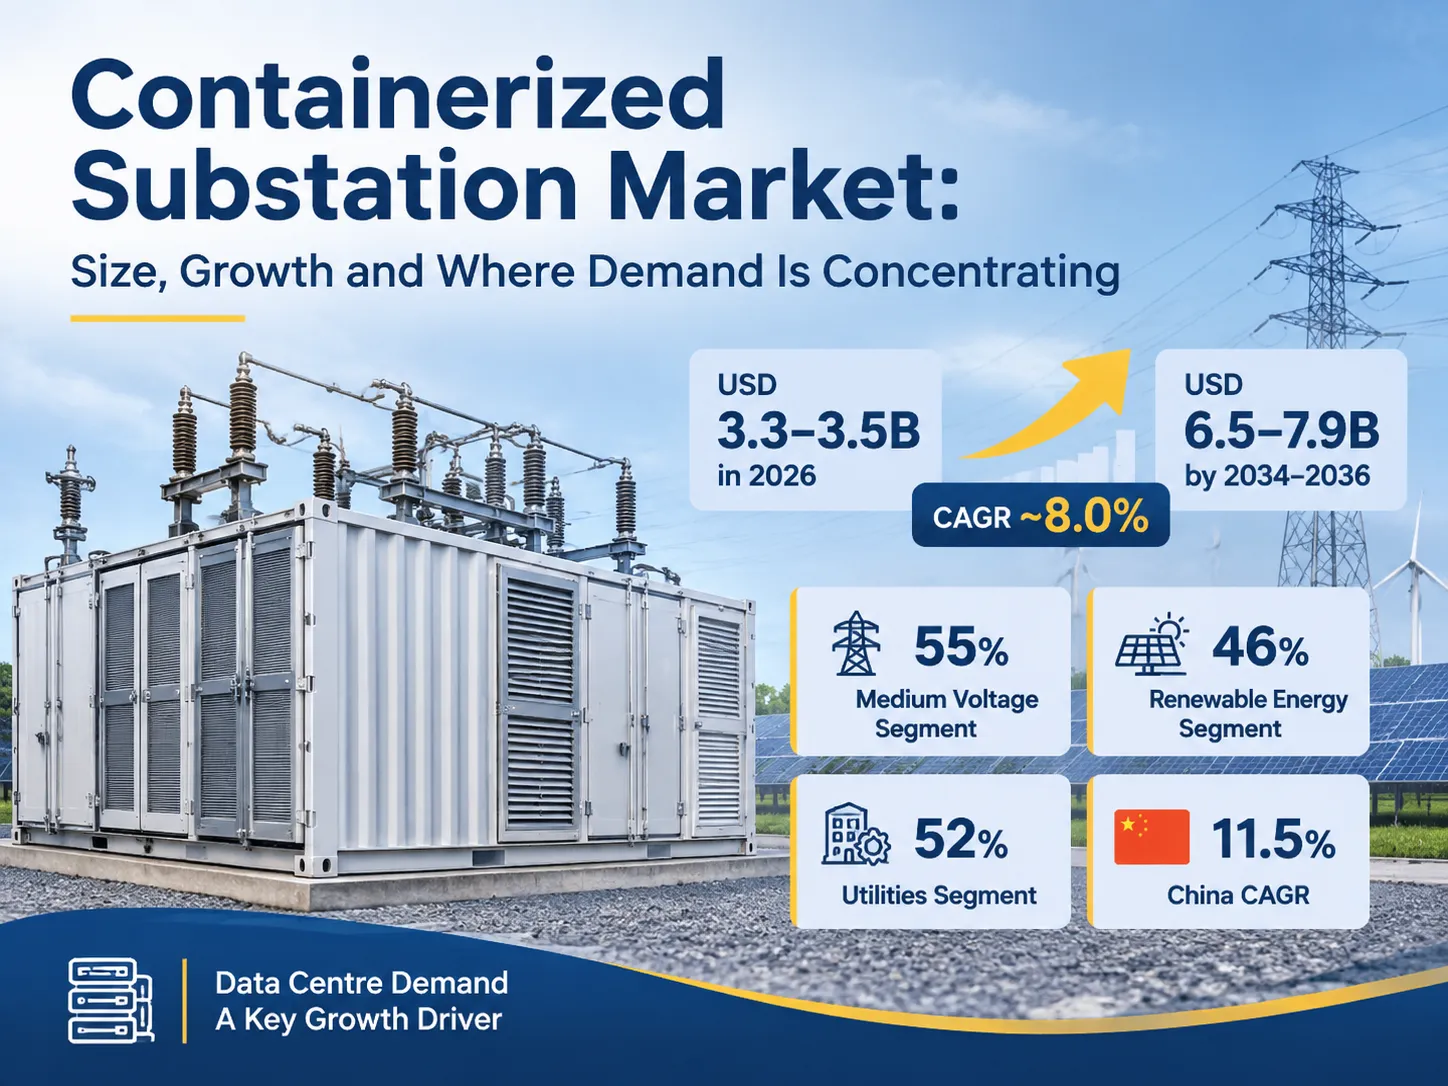
Um meine frühere Spekulation zu vereinfachen, wird die Gesamtgröße oder der Gesamtwert des Marktes für containerisierte Umspannwerke im Jahr 2026 auf zwischen 3,3 Milliarden USD und 3,5 Milliarden USD geschätzt. Die prognostizierte jährliche Wachstumsrate (CAGR) liegt bei etwa 8,01 %, was diesem Markt erlaubt, bis 2034 bis 2036 auf einen Wert zwischen 6,5 Milliarden USD und 7,9 Milliarden USD zu wachsen. Fünfundfünfzig Prozent (55 %) des erwarteten Umsatzes werden voraussichtlich aus dem Mittelspannungssegment stammen, während das größte Segment des erwarteten Umsatzes aus dem Segment der erneuerbaren Energien (46 %) des Gesamtmarktumsatzes kommen wird. Zweiundfünfzig Prozent (52 %) werden aus dem Versorgungssegment des Gesamtmarktes stammen, und das am schnellsten wachsende Land wird China sein, mit einem jährlichen Wachstum von 11,5 % in der Zukunft. Die Nachfrage von Rechenzentren wurde in allen Prognosen von 2021 nicht ausreichend berücksichtigt.
Warum drei Berichte drei unterschiedliche Zahlen liefern
Die bisher veröffentlichten drei Berichte haben alle eine Prognose für das zukünftige Marktwachstum geliefert. Es besteht Konsistenz in den Berichten hinsichtlich der prognostizierten prozentualen Wachstumsraten, jedoch unterscheiden sie sich in der absoluten Marktgröße. Folglich verwenden alle drei Berichte unterschiedliche Bewertungsmethoden. Es ist offensichtlich, dass es weiterhin Marktwachstum im Bereich der vorgefertigten und tragbaren Unterverteilungs-Umspannwerke geben wird, bedingt durch die Geschwindigkeit, mit der neue Netzanschlüsse hergestellt werden müssen, um die steigende Nachfrage zu ermöglichen, wie im untenstehenden Diagramm dargestellt.
| Quelle | Basisjahreswert | Prognosewert | CAGR | Was ist enthalten |
|---|---|---|---|---|
| Future Market Insights | 3,20 Mrd. USD (2025); 3,47 Mrd. USD (2026) | 7,85 Mrd. USD (2036) | 8.5% | Markt für vorgefertigte tragbare Unterverteilungs-Umspannwerke |
| The Insight Partners | 3,27 Mrd. USD (2025) | 6,56 Mrd. USD (2034) | 8.04% | Gleiche Produktlinie, segmentiert nach MVA-Band einschließlich über 100 MVA |
| Reanin | 1,32 Mrd. USD (2025) | 2,09 Mrd. USD (2032) | 6.7% | Engere Definition, näher an skid-montierten tragbaren Umspannwerken |
Aus den oben dargestellten Daten ergibt sich ein allgemeiner Konsens, dass der Gesamtmarkt für tragbare und vorgefertigte Unterverteilungen heute (2025) zwischen $3B – $4B liegen wird, mit einer entsprechenden Marktwachstumsrate von etwa 7 – 9%. Reanins Prognose liegt ungefähr bei einem Drittel der beiden anderen Berichte; dies ist jedoch wahrscheinlich darauf zurückzuführen, dass Reanin die größeren vorgefertigten tragbaren Gebäude ausschließt und nur die kleineren verpackten Unterverteilungen zählt, die in die Definition von containerisierten Anlagen fallen. Dies ist dasselbe Produkt, das die meisten Industriekunden verwenden, wenn sie sich auf containerisierte Umspannwerke beziehen, daher ist die kleinere Zahl nicht falsch, sondern eine weniger umfassende Auffassung des tragbaren/vorgefertigten Unterverteilungsmarktes, wie er in Reanin dargestellt wird. Für jeden einzelnen Käufer sind die relevanten Informationen die Marktsegmente, an denen er interessiert ist, und nicht die Gesamtmarktzahl.
Ein Käufer muss feststellen, ob die Lieferzeiten zunehmen, ob das Marktsegment, in dem er kauft, das Hauptsegment ist, das zusätzliche Kapazitäten aufnimmt, und welche Länder eine wettbewerbsfähige Verfügbarkeit von Fabrikslots bieten.
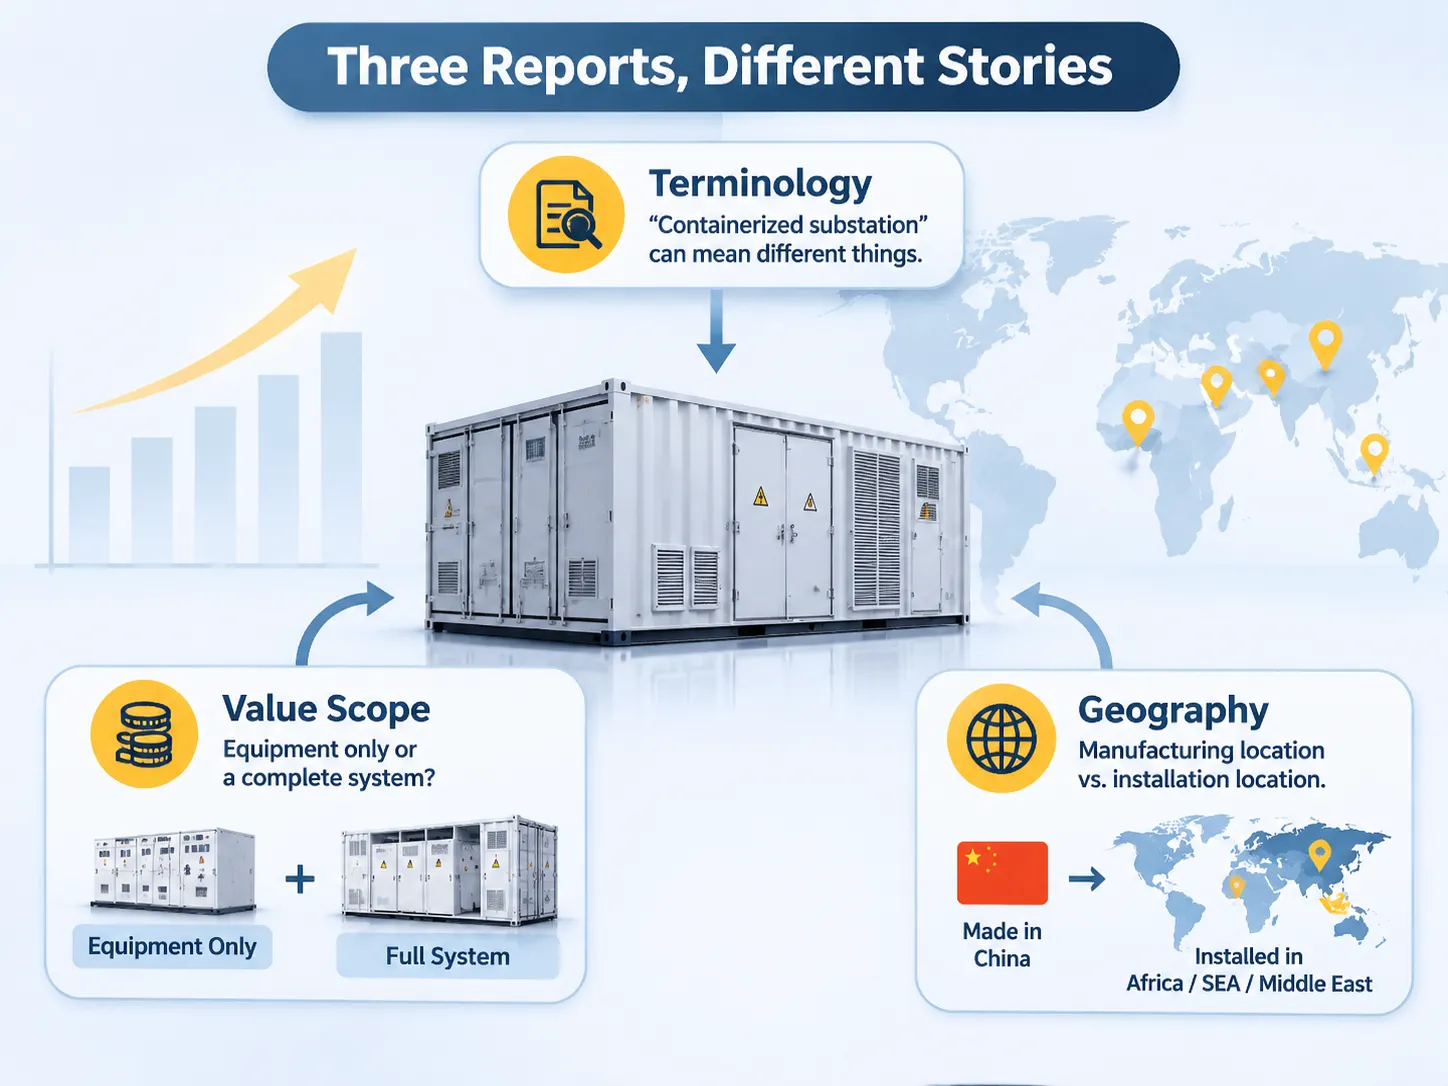
Wenn drei Forschungsberichte dasselbe Produkt unterschiedlich beschreiben
Die Diskrepanz in den verwendeten Begriffen für diese Produkte stellt das größte Hindernis bei der Durchführung einer genauen Marktforschung zu diesem Produkt dar, gefolgt von der Qualität der in den jeweiligen Berichten gemeldeten Daten. Der Begriff “containerisiertes Umspannwerk” kann verwendet werden, um eine Vielzahl von Produkten zu beschreiben, die außer der Tatsache, dass sie als “Container” versandt werden, nur wenig gemeinsam haben. Zusätzlich zum Verkauf durch verschiedene Unternehmen als containerisiertes Umspannwerk definieren auch verschiedene Hersteller das Produkt unterschiedlich.
Ein weiterer entscheidender Punkt zur Unterscheidung der drei Berichte ist die Methode, mit der sie bestimmen, welcher Wert des Umspannwerks gezählt wird. Zum Beispiel kann der Umsatz mit Umspannwerksausrüstung allein im Vergleich zu einem kompletten System (mit Hilfseinrichtungen, Schutz, HVAC und Brandschutz) erhebliche Unterschiede zwischen den drei Berichten verursachen. Umspannwerke, die als getestete Baugruppe geliefert werden, erzielen aufgrund der Einbeziehung aller notwendigen Komponenten in der getesteten Einheit einen Wert, der drei- bis fünfmal so hoch ist wie der Wert der Umspannwerksausrüstung allein, und daher, liefert ein Bericht, der nur den Ausrüstungsumsatz erfasst, eine deutlich niedrigere Umsatzzahl als ein Bericht, der den Gesamtumsatz des Systems erfasst..
Schließlich führt der geografische Unterschied zwischen den geografischen Standorten der Herstellung und der Installation zu enormen Abweichungen zwischen diesen drei Berichten.
Zum Beispiel wird ein erheblicher Prozentsatz der containerisierten Umspannwerke, die in den Städten Afrikas/Südostasiens/Mittleren Ostens installiert werden, im Land China produziert.
Daher würde ein Bericht, der das Installationsland repräsentiert, einen erheblichen Marktanteil erfassen, der in diesen Regionen auftritt, während ein zweiter Bericht, der das Herstellungsland repräsentiert, einen vergleichsweise geringeren Marktanteil anzeigen würde. Was als containerisiertes Umspannwerk zählt und was nicht Ein Container-Umspannwerk wird in diesem Dokument als ein werkseitig montiertes und getestetes Umspannwerk beschrieben, das als eine Einheit (oder möglicherweise zwei oder mehr Einheiten) zum Standort geliefert wird und vor Ort verdrahtet (aber nicht montiert) wird, um den Versorgungsdienst für Kunden bereitzustellen.
Kompakt-Umspannwerkskonfigurationen Referenzleitfaden
definiert die Arten von Gehäusen, die dieser Definition entsprechen, einschließlich eines vielseitigen Einzeltransformator-Kiosks bis hin zu einem begehbaren Paket mit einem Niederspannungsraum.
Was ist kein containerisiertes Umspannwerk?.
Eine Definition für containerisierte Umspannwerke umfasst die unten aufgeführten Gehäusetypen; ein Standard-Umspannwerksgebäude mit gegossenen Böden und Mauerwerkswänden erfüllt jedoch nicht die Definition eines containerisierten Umspannwerks, selbst wenn die Schaltanlage in kompletten Modulen geliefert wird.
Ein mobiler Generator, der in einem Standardcontainer untergebracht ist, erfüllt nicht die Definition eines containerisierten Umspannwerks.
| Land | Ein containerisiertes Paket-Umspannwerk ohne Schaltanlage (nur Transformatoren in Gehäusen) wird in der Regel als Transformatorprodukt und nicht als Umspannwerk gezählt. | Für den Käufer entsteht dadurch ein praktisches Problem, da die von den Lieferanten angegebenen Preise in der Regel nicht vergleichbar sind, z. B.: Ein Lieferant, der ein „1.000 kVA containerisiertes Umspannwerk“ anbietet, könnte einen in einem Container verpackten Transformator anbieten, während ein zweiter Lieferant ein komplettes Paket einschließlich Schutz, Messung, Hilfseinrichtungen, dokumentiertem und getestetem Bericht (Routine) bereitstellen könnte. |
|---|---|---|
| China | 11.5% | Daher ist es entscheidend, dass die Spezifikation den Leistungsumfang ausdrücklich angibt und nicht nur eine Produktkategorie. |
| Indien | 10.7% | Wachstum nach Ländern und was es tatsächlich antreibt |
| Deutschland | 9.8% | Die Wachstumsraten der Länder für 2026 sind ein umsetzbarer Teil des Forschungsberichts, da sie aufzeigen, wo die Nachfrage nach allen Umspannwerksausrüstungen und -dienstleistungen konzentriert ist, anstatt nur zu identifizieren, wo die Nachfrage derzeit liegt (sie zeigen, wo die Nachfrage für 2026 geschätzt wird). |
| Optimierungsmaßnahmen in der Praxis | 8.9% | CAGR 2026 bis 2036 |
| Was es antreibt | 8.1% | Offshore Wind Land Fall Substations. A must for Grid Stability and backup during storms and emergency situations; mobile unit production will assist in areas lacking access to the grid. |
| USA | 7.2% | The Distribution of Data Centres is driving Utility Grid Modernisation and the creation of a Storm Resilient Utility Grid in the US. |
| Brasilien | 6.4% | Hydro and solar plants connected to the grid, industrial clusters’ ability to export. |
The pattern is that where the grid is extended and not replaced (new factories using prefabricated units) there is more rapid growth than for markets that have mature grids with more mature & complex products. Thus, while the US market is still one of the two biggest in value, it has had the slowest growth rate on this list.
The most frequently cited limiting factors (as opposed to drivers) according to this particular report and other similar reports are Permitting and Interconnection Queues, in this order. This is consistent with what Commercial Companies see. The Equipment itself is rarely considered to be the long pole, whereas it is the Grid Connection Studies that are.
Data Centres: The Demand Line Nobody Modelled in 2020
In 2021, the reports listed the following four markets as Renewable Energy Mines, Temporary Supply Energy and Disaster Recovery. Data centers were not included in previous projections as populated by the IEA through 2026, but have since changed to explain the rise in data center forecasts, with currently still published Segments Tables showing Renewable Energy as the largest category.
Evidence of this can be found in electricity consumption numbers. The IEA predicts global electric consumption from data centers to reach 415 TWh (approximately 1.5% of total global electric consumption) within 2024, while projecting over 2X increase in electric consumption from data centers to approximately 945 TWh by 2030. Approximately 45% of global electric consumption will be attributable to data centers and the anticipated electric demand growth from data centers is estimated to comprise approximately 50% of all electric demand growth in the U.S. during this same time period.
The implications for this product are as follows: Hyperscale campuses require 100 MW of electricity and above – to be delivered in phases. In addition, the medium voltage distribution for each phase must be separated and metered from each other. A containerised substation can be ordered and factory tested and energized within months; it can also be reused at another site once the initial site has been developed and ready for use. The primary advantage of this approach is based on schedule and there’s no monetary value associated with this product; it is what data center clients wish to purchase.
There are similarly specific constraints associated with this product. The IEA estimates that 20% of planned data center developments will be subject to delays due to insufficient grid connections. At present, substation packages do not eliminate the queue for.
Source: IEA World Energy Outlook 2023, JLL.
The two major applications for the current generation of substations are renewable integration (46.2% of total sales by 2026) and mining (2nd plus extreme requirements). Structural reasons support why the largest revenue generator for renewable integration is solar farms (which typically are located in remote locations with no roads or buildings). To accommodate this characteristic, a complete substation must be supplied at the time of the farm’s construction.
While a wind farm has similar characteristics as a solar farm, the multiple collection points of a wind farm create additional challenges when supplying substations.
Mining substations represent the second largest revenue stream and have the most extreme requirements of any substation type. Mining sites are mobile, and therefore substations must also be mobile. For example, a mining substation located at 2,000 metres above sea level causes the switchgear to derate and alters the creepage distances.
Also, due to the dominant load of large drives used in mining operations, harmonic distortion and a specification stating the short-circuit current must be included.
Finally, the two remaining types of station are temporary supply and disaster recovery.
Temporary supply and disaster recovery are both used for temporary purposes; however, they differ from the other two applications’ customers because their customers are typically either a utility or a rental company rather than a project developer.
When mobility is a key consideration of prefabricated outdoor substations, specifications for these units must reflect that characteristic.
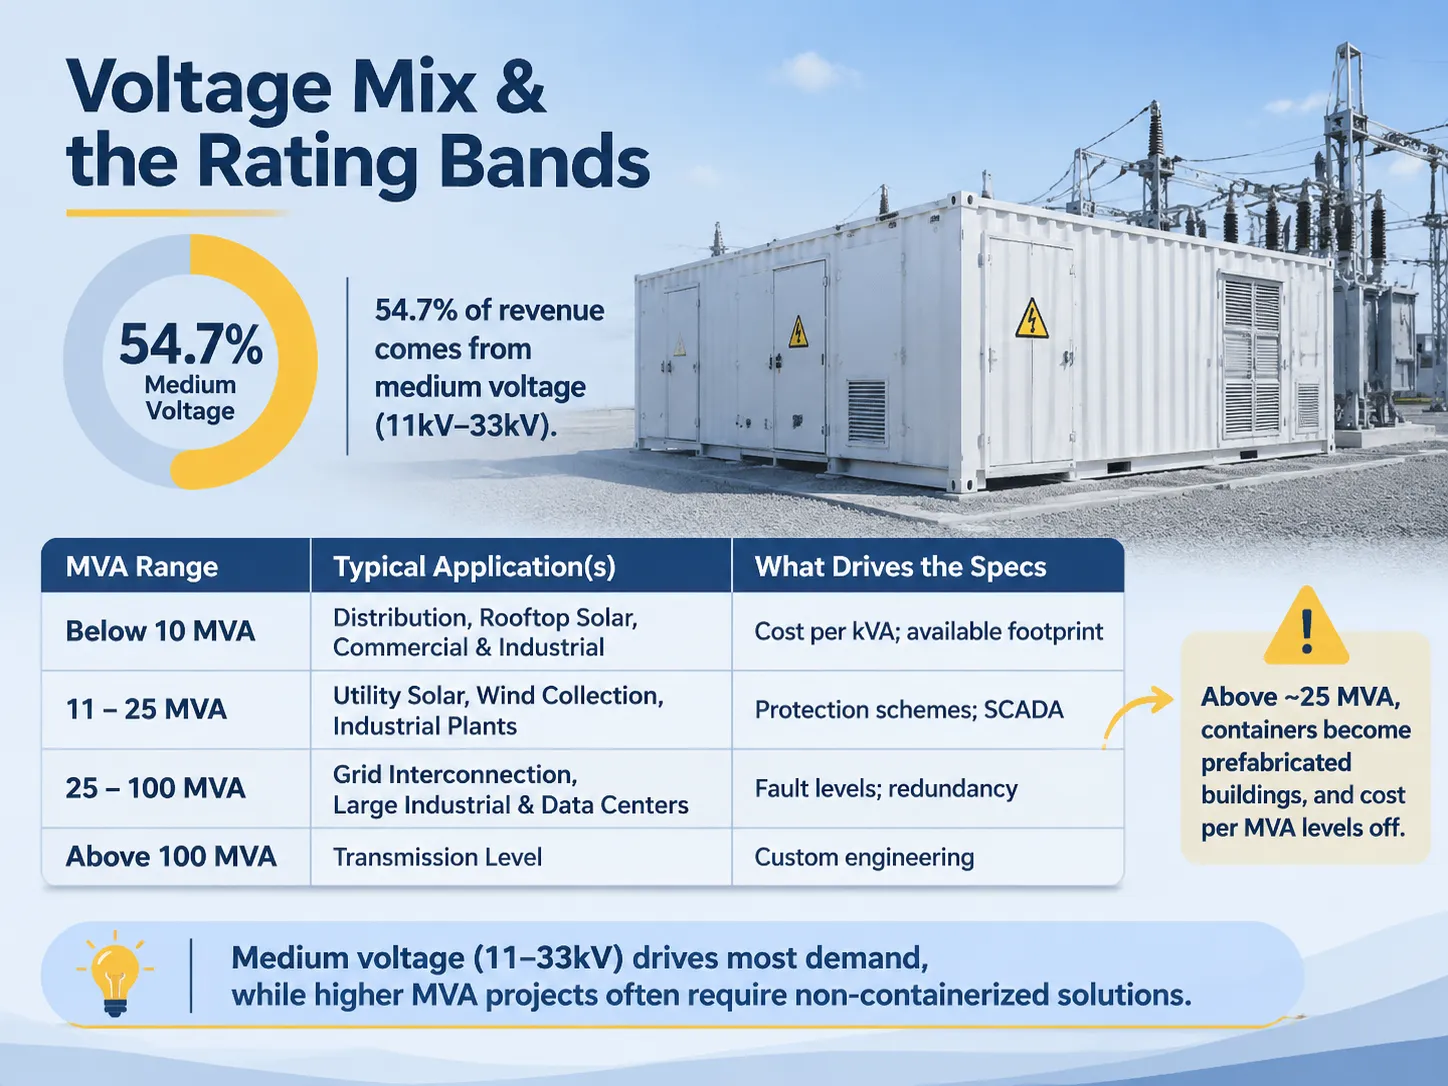
Voltage Mix and the Rating Bands Buyers Order
54.7% of total revenue will be generated by medium voltage, which is consistent with what will be installed. Most containerized substations are rated 11kV, 22kV, or 33kV on the primary side and 400V or 480V on the secondary side, because it is more economical to construct a factory-built package in this voltage band than it is to build a factory.
The segmentation of MVA used for research publications provides a better approximation of the actual items sold than voltage split by segmenting the market by application almost exactly.
| MVA range | Typical application(s) | What drives the specs |
|---|---|---|
| Below 10 MVA | Distribution, Rooftop and Ground-Mounted Solar, Commercial and Industrial Facilities | Cost per kVA; available foot print; standardized enclosures. |
| 11 to 25 MVA | Utility Scale Solar Blocks, Wind Collection, Industrial Plants | Protection schemes; SCADA; harmonic distortion limits. |
| 25 to 100 MVA | Interconnection to the grid, Large Industrial and Data Center Complexes | Fault levels; redundancy; metering; compliance. |
| Above 100 MVA | Transmission Level, Generally Not Containerized Unless Used as an E-House | Custom engineering; transport limits; assembly on-site, etc. |
When MVA is above approximately 25 MVA, containers no longer qualify as products but become buildings designed for prefabrication. At that point, the cost per MVA trend begins to level off, so specifiers should be aware of this limitation when making assumptions about continuing economies of scale beyond this range.
Who Is Winning: Tiers, Names and Regional Strength
The competitive landscape can be viewed in three tiers, though no sample market shares have been released. Tier One are global electrical leaders; Tier Two are large regional manufacturers; Tier Three includes a long list of national factories and specialty manufacturers.
Tiers One — ABB, Siemens Alliance, Siemens Energy, Eaton, Schneider Electric and GE. Their advantage lies in the product inside the container: the protection and control systems, the type test documentation, and the utility writing specifications based on their equipment is less contentious than challenges to those specifications. Companies such as Toshiba, Larsen & Toubro, Kirloskar, Crompton Greaves, IMESA, Elsewedy, Meidensha, Powell and Qingdao TGOOD are all examples of manufacturers that fall into Tier Two. Each of these Tier Two manufacturers has a large presence in their respective home geographies as well as in the different market segments that tier two sets the standards for.
Most projects are completed in tier three. This is not a weakness of the tier three market. For example, a 2 MVA distribution package for a solar farm located in Southeast Asia will not require a global protection platform. It will need to contain a compliant transformer, a type tested ring main unit, a documented routine test that covers both the Transformer and Ring Main Unit, and a delivery date.
The elements of the monitoring layer form the basis of the competition in tier three. About half of all new installations now include some form of remote monitoring for the temperature, partial discharge trends, and breaker status information as standard features; this is what the intelligent integrated substation range provides. Although a small additional expense to the package, the intelligent integrated substation capability represents a significant increase to the service contract’s costs and is therefore being adopted by tier three suppliers at a significantly faster rate than their tier one counterparts. In addition, two recent product announcements illustrate the competing priorities between the major manufacturers as they pursue growth. In June 2023, Schneider released its containerized microgrid solution aimed at integrating renewable energy resources off the grid. In October 2022, Siemens Energy introduced a containerized substation for access into emerging markets, especially Africa. Both manufacturers have recognised this is where the bottleneck exists within the grid’s connection to each company’s product offerings.
What the Market Data Does Not Tell a Buyer
The most important piece of information that a buyer needs to know before they look to purchase is the price per MVA, which is not provided in any of the summaries available to the public. The only information currently available to buyers is the pricing range of the different packages that include Transformer, MV Switchgear, LV Distribution, and Basic Protection Packages, which appear to average USD $80,000 – 200,000 for a 1 MVA and USD $500,000 – 1.2 million for a 10 MVA. The difference in prices within each category reflects the scope of work involved, as opposed to the profit margin for any individual company.
Another significant piece of information that is missing from the published data is the estimated lead time for equipment delivery. A 1 to 2.5 MVA standard distribution package will generally be available 12 – 20 weeks after placing a factory order with the manufacturer, primarily because the Transformer and Ring Main Unit are standard catalogue products. However, an End-User Utility specification with a custom protection scheme and factory witness testing and a defined short circuit study will take between 6 – 9 months to complete, primarily due to the need for Engineering Approval rather than the time involved in the manufacturing process.
The last important piece of data missing from the published market data is the site development cost associated with the equipment that the Buyer is attempting to replace with a containerised solution. The containerised solution will still require a foundation, cable trench, earth grid and connection agreement. Based on the Manufacturer’s claims, the site development costs and resulting speed of installation of a containerised solution are, in fact on average, 25 – 30% lower in comparison to building a brick structure, but this comparison is misleading. The comparison being made in the published data is to a fully functional transformer that is located on a foundation.
Where Subian Fits in This Market
Subian provides the majority of our volume when it comes to medium voltage distribution packages that range from several hundred kVA to approximately 10 MVA. Our packages can be supplied in both an enclosure-type box structure or as a containerized assembly, which includes the distribution transformer and all required MV and LV switchgear and LV distribution components pre-assembled and factory-tested prior to leaving the manufacturing facility. This accounts for approximately 54.7 percent of the overall market as discussed in this report, and it is where the factory with a dedicated transformer manufacturing facility has an advantage over integrators who do not have this capability and must purchase the transformers.
Subian’s offering in the distribution transformer and substations includes all standard configuration options: 11, 22 and 33 kV primary voltage, 400 to 480 volts secondary voltage, ONAN or ONAF cooling, and enclosure options available in painted steel, galvanized steel, or stainless, depending on where the equipment will be located. Subian’s employees configure the monitoring systems for each customer based on their specific requirements. Therefore, there is no “standard” for monitoring configurations, since it is likely that a mining customer who has no communication link will not wish to purchase telemetry that he/she cannot use.
Subian does not position itself to compete with the larger tier one providers; to do so would result in wasted resources for both sides. If a project specification requires any of the following: a global protection scheme, a specific type of relay, or a utility-type test certificate, the tier one providers will provide a superior product to Subian, therefore we would expend resources unnecessarily for both parties by quoting on this type of project. Conversely, when a project specification is performance-driven, the same type of performance rating is available at a different cost and lead time.
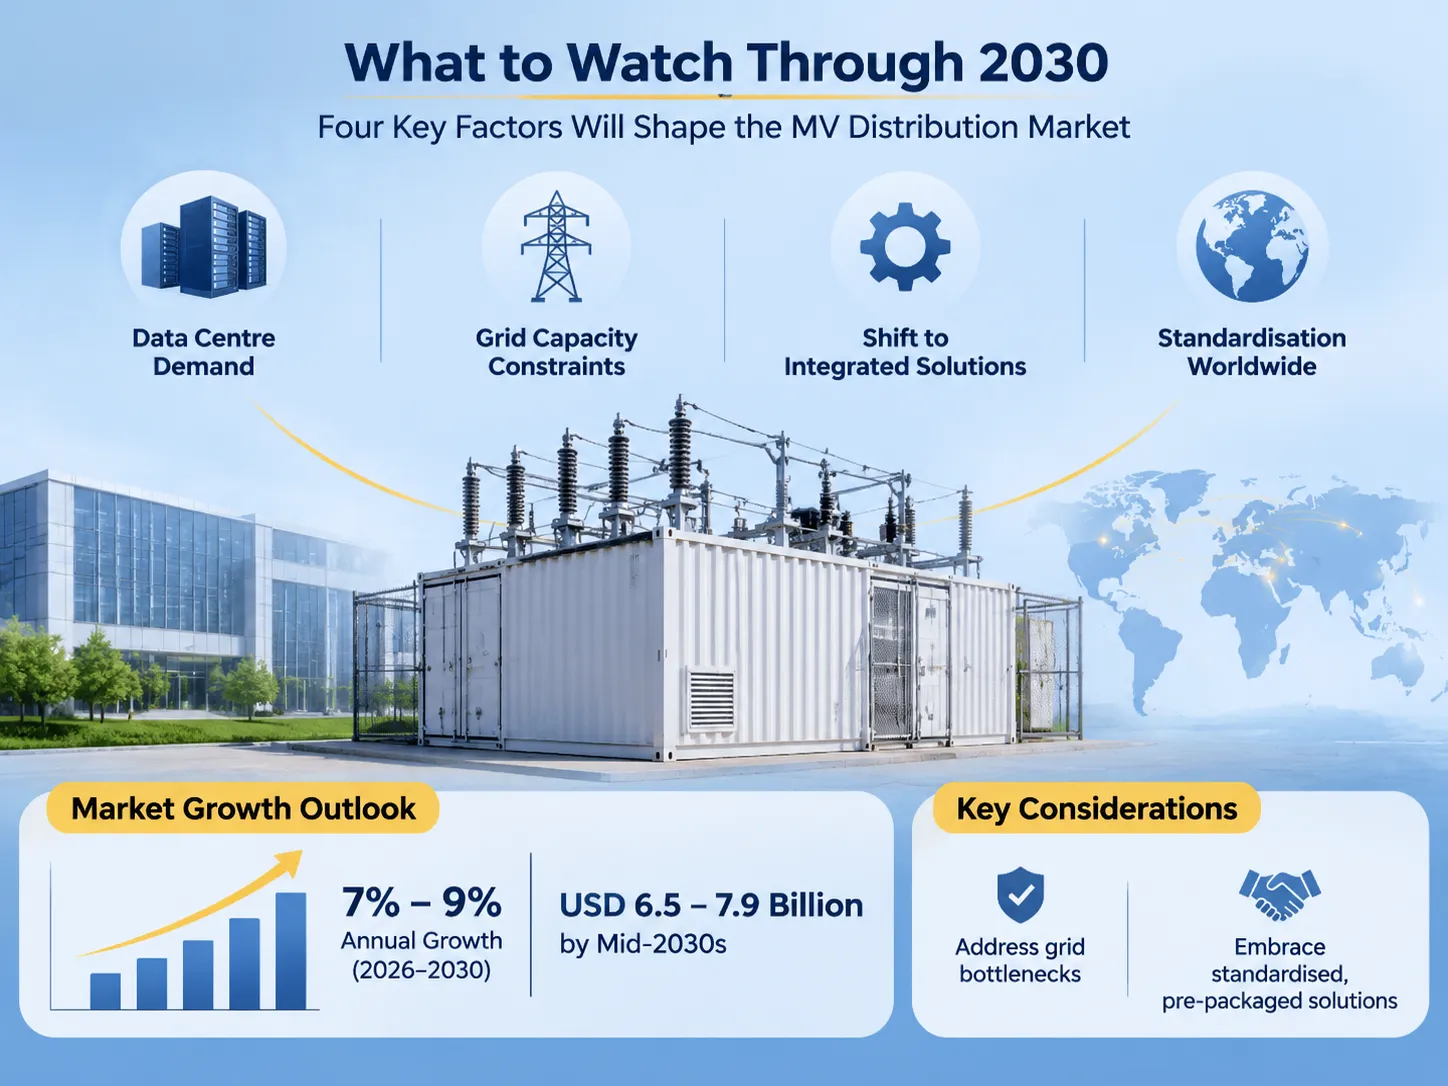
What to Watch Through 2030
By 2030, the continued state of the medium voltage distribution market will be driven by the following four factors, with only three factors visible in the data to date:
The following areas are potential barriers to developing a sizable global containerized substation market:
- Daily growth of the data centre segment exceeds expectations according to most specialised publications. This suggests that the average size of a data centre will continue to increase, leading to a decrease in the number of smaller manufacturing facilities that supply to the sector. This is due to the fact that a typical 100 MW data centre buyer does not typically use a product catalogue for purchasing.
- There is insufficient capacity on the electrical grid to support large scale data centre development. A significant number of proposed data centres are currently experiencing construction delays due to the limited capacity of the grid. Therefore, product availability to shorten construction is not likely to have any effect on the length of time it takes to complete the necessary studies to obtain a construction permit. This situation will likely serve to limit the ability to grow in high-demand markets.
- There is a major transition from the sale of individual pieces of equipment to the sale of pre-packaged solutions. Recent reports indicate that approximately 50% of the data centre systems installed today are being monitored remotely. An even larger percentage (approximately 65%) of respondents to a recent survey indicated that they plan to increase their investment in remote monitoring solutions. As such, customers will be purchasing uptime and reporting, as opposed to buying the actual hardware.
- Countries are moving toward adopting standards. Each country has its own MV standard voltage. Each country also has its own MV design philosophy and each country has its own route of approval. A manufacturing operation that can offer three or four configurations in tooling will have a competitive advantage over an operation that is developing a new configuration for every order. The international comparison of substations provides examples of how these configurations vary throughout the world and represents the pragmatic continuation of this movement toward standardisation.
A market report released over the fall of 2026 predicted between USD 3.3 billion and USD 3.5 billion in revenue, a narrower definition placing it closer to USD 1.3 billion. In 2026, the annual growth forecast is expected to be between 7 per cent and 9 per cent with values at mid-2030s ranging from USD 6.5 billion to USD 7.9 billion depending on the scope.
FAQ
Why are there contradictions among the size of the market in certain reports?
Market reports disagree with one another because they define the product differently: some are based on equipment revenue, whereas others include the delivered packaged product, including all protection, auxiliaries and testing. Some count large volumes of prefabricated buildings, whereas others count cargo crates and skids. The growth rate between market reports is more closely aligned than the total value.
Which region is experiencing the most growth?
China is experiencing the most rapid growth at approximately 11.5 per cent annually through 2036, followed by India at about 10.7 per cent. Both regions are ‘growing out’ rather than ‘replacing’ existing grids, which allows factory-built units to offer the fastest delivery times. While the United States is the slowest growing region among large markets and the growth is expected to be approximately 7.2 per cent, it is also a large market based on the financial value of its units being larger.
Are data centres currently driving the growth of the containerized substation market?
Currently, data centres are the fastest growing application for containerised substations; however, data centres are not yet the largest segment in the published tables. Published tables report renewable integration accounts for approximately 46 per cent of total sustained demand. The electricity consumed by data centre demand is found in the electricity statistics: a projected 415 TWh of electricity consumption in 2024 increasing to around 945 TWh in 2030, with approximately 45 per cent of consumption occurring within the United States.
What is the typical size substation that is packaged as a containerised substation?
The majority of packages will typically be less than 25 MVA and most packages will have a volume rating of less than 10 MVA. When packages exceed 25 MVA they become prefabricated buildings, and when they exceed 100 MVA they become E-Houses which are custom designed and assembled on site. The per MVA price will cease to fall at this transition.
What is the lead time to receive a containerised substation package?
Lead times for containerised substation packages will vary between twelve and twenty weeks for standard 1 to 2.5 MVA distribution packages, as the transformer and switchgear are catalogue products. Lead times for Utility Specification Containerised Substation packages will be six to nine months, and the reason for this delay is due to the need for customised protection and completion of engineering approvals versus actual production timelines.
Referenzen
- Future Market Insights — Containerized Substation Market
- The Insight Partners — Containerized Substation Market
- Reanin — Containerized Substation Market
- IEA — Energy and AI
- Hitachi Energy — Grid and Substation Technology
Fazit
Der Markt für containerisierte Umspannwerke wird voraussichtlich ein Geschäft im Wert von 3 bis 4 Milliarden USD sein, mit einer erwarteten Wachstumsrate von 7% bis 9%, wobei die Diskrepanz zwischen den Berichten darauf zurückzuführen ist, dass sie sich in ihrer Definition desselben Marktes widersprechen, obwohl sie auf ähnlichen Datenquellen basieren. Derzeit stammt der größte Umsatzanteil im Markt für containerisierte Umspannwerke aus der Integration erneuerbarer Energien, Versorgungsunternehmen und Mittelspannungsmärkten. Die Nachfrage aus Rechenzentren wird zu Änderungen der aktuellen Prognosen führen.
For purchasers of containerised substations, it will be important to remember that the lead time for receipt is based on engineering approvals and not on factory capacity, and that the value of ratings under 10 MVA are the valued segments. In addition, that the specifications of a product, not its category, determines which two quotations can be compared against each other.